Categories
Charlotte Real Estate, Charlotte Real Estate Market, Homebuyer Education, Home Buying, Market Updates, Mortgage & Financing, ITINPublished September 29, 2026
Can You Buy a House With an ITIN in North Carolina? | DZ Pro Realty
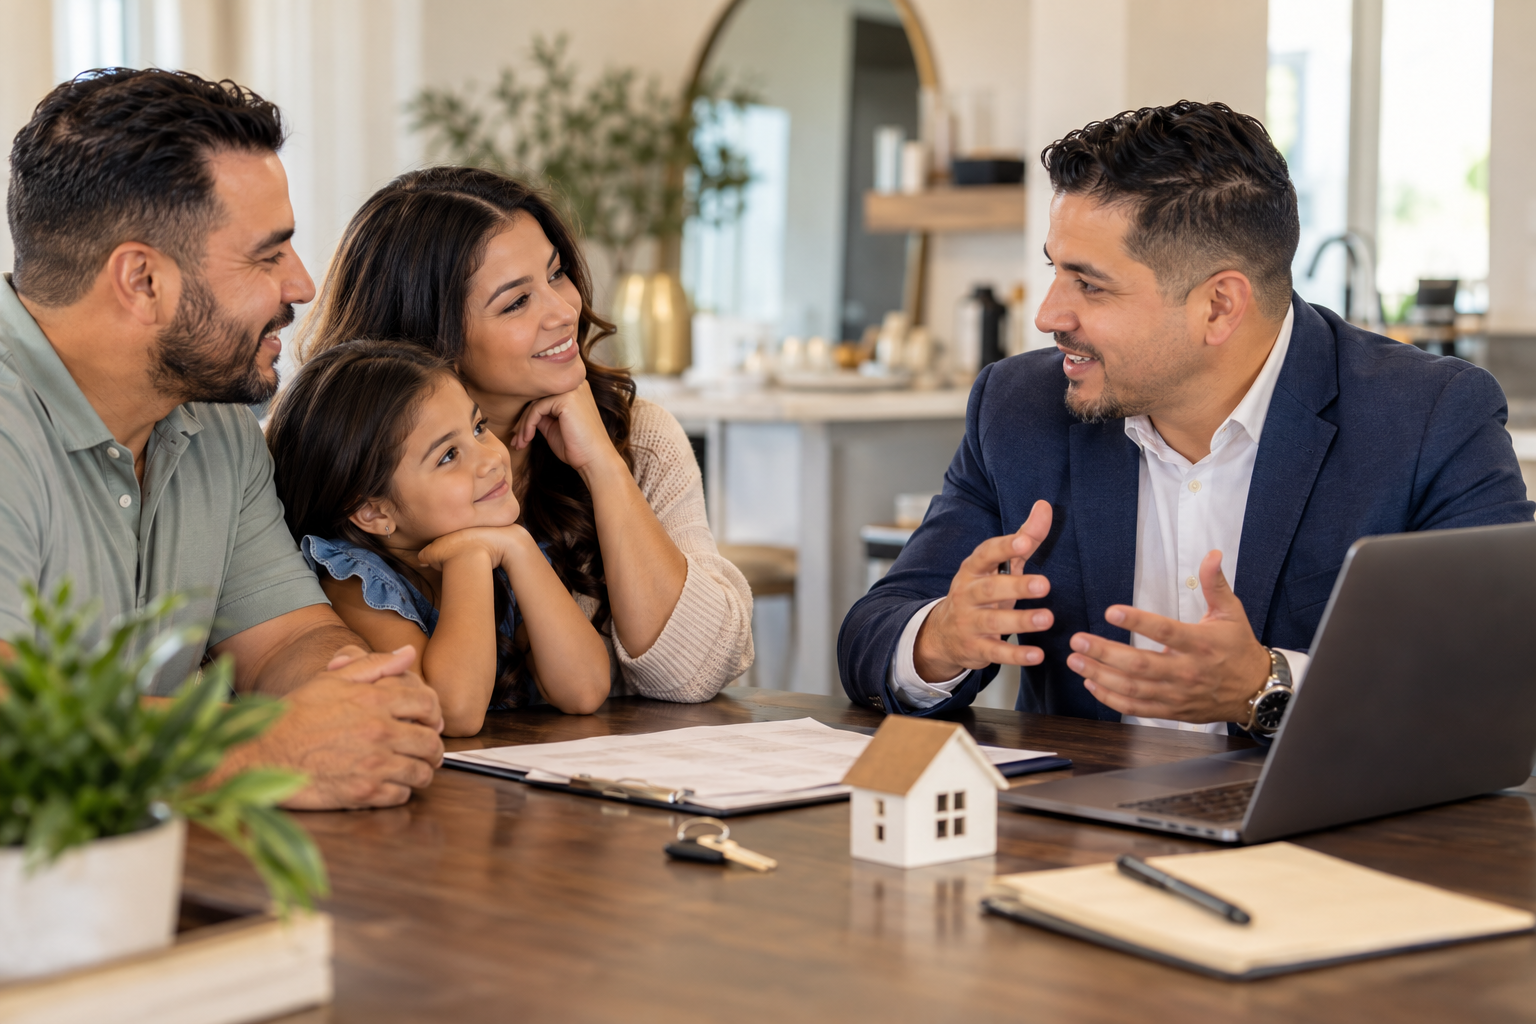
Can You Buy a House in North Carolina With an ITIN Number?
For many families, owning a home represents more than having a place to live. It can mean stability, putting down roots in a community, building equity, and creating something that can eventually be passed on to the next generation.
But if you have an Individual Taxpayer Identification Number (ITIN) instead of a Social Security number, you may have wondered:
Can I actually buy a house in North Carolina with an ITIN?
The answer may surprise you: having an ITIN does not automatically prevent you from becoming a homeowner.
There are lenders and mortgage programs that work with ITIN borrowers. However, the process can look different from traditional mortgage financing, and requirements can vary significantly from one lender or program to another.
At DZ Pro Realty, we believe you shouldn't assume homeownership isn't possible simply because your financial situation looks different. The first step is understanding your options and creating a plan based on your individual circumstances.
What Is an ITIN?
An Individual Taxpayer Identification Number, commonly called an ITIN, is a tax-processing number issued by the IRS to certain individuals who need a U.S. taxpayer identification number but aren't eligible for a Social Security number.
An ITIN allows individuals to comply with federal tax laws, but it does not provide immigration status, employment authorization, or eligibility for Social Security benefits.
When it comes to buying real estate, however, the important question isn't simply whether you have an ITIN. It's whether you can find financing appropriate for your circumstances.
And for some buyers, that may be possible.
Can You Get a Mortgage With an ITIN?
Yes, there are lenders that offer mortgage financing to eligible ITIN borrowers.
However, there isn't one universal “ITIN mortgage” with the same rules everywhere.
Different lenders and loan programs may have different requirements for:
- Down payment
- Income and employment history
- Tax returns and income documentation
- Credit history
- Debt-to-income ratio
- Bank statements and assets
- Cash reserves
- Property eligibility
- Interest rates and loan terms
That's why comparing your situation to a friend, relative or coworker can sometimes create confusion.
You may hear:
“My cousin bought with an ITIN and only needed this much.”
Or:
“Someone told me you can't buy without a Social Security number.”
Neither person's experience necessarily determines what will happen in your situation.
Every buyer's financial picture is different, and the lender ultimately determines whether a borrower qualifies for a particular mortgage.
What Will a Lender Look At?
Having an ITIN is only one part of the financial picture.
A lender still needs to determine whether you can reasonably afford the mortgage and meet the requirements of the loan program being considered.
Here are some of the areas that may be evaluated.
1. Your Income and Employment
One of the biggest questions a lender needs to answer is:
Can this borrower reasonably afford the mortgage payment?
Depending on the loan program and your employment situation, you may be asked to provide documents such as tax returns, pay stubs, bank statements or other proof of income.
Stable and properly documented income can play an important role in the mortgage qualification process.
If you're thinking about buying a home in the future, keeping organized financial and tax records can make the process much easier when you're ready to speak with a lender.
2. Your Credit History
Another common misconception is:
“If I don't have a Social Security number, my credit doesn't matter.”
That isn't necessarily true.
Lenders still need a way to evaluate how you've handled financial obligations in the past. The way credit is evaluated can depend on the lender and mortgage product.
If you have established credit, your credit history may be reviewed. In some circumstances, lenders may also have guidelines for evaluating borrowers with limited traditional credit history.
Don't assume that having little credit—or imperfect credit—automatically means homeownership is impossible.
A lender familiar with ITIN borrowers can review your individual situation and explain what may need improvement.
3. Your Down Payment
This is one of the biggest questions we hear from potential homebuyers:
“How much money do I need?”
Unfortunately, there isn't one number that applies to everyone.
Some specialized ITIN mortgage programs may require larger down payments than certain traditional mortgage programs. Requirements can vary considerably depending on the lender, borrower and loan product.
That's why you shouldn't automatically spend another year saving because someone told you that you need a particular percentage down.
Talk to a qualified lender first.
You may learn that you need to save more. You may discover you need to focus on something else first. Or you may find that options exist that you didn't know were available.
The goal is to replace assumptions with actual information.
4. Your Existing Debts
How much money you earn is only part of the equation.
A lender may also evaluate your existing monthly financial obligations, such as:
- Car payments
- Credit card balances
- Personal loans
- Other recurring debts
This is why two families earning exactly the same amount of money could potentially qualify for very different mortgage amounts.
Your overall financial picture matters.
And qualifying for a certain amount doesn't necessarily mean you should spend that amount.
At DZ Pro Realty, we believe there's another important question buyers should consider:
What monthly housing payment would allow my family to own a home comfortably while still accomplishing our other financial goals?
Buying a home should be part of your financial plan—not the entire financial plan.
5. Your Savings
The down payment isn't necessarily the only expense associated with purchasing a home.
Depending on the property, financing and transaction, buyers may also encounter expenses related to things such as:
- Inspections
- Appraisal
- Closing costs
- Homeowners insurance
- Prepaid expenses
- Due diligence or earnest money
- Moving expenses
- Immediate homeownership expenses
Some lenders may also require borrowers to have additional financial reserves.
That's why preparing for homeownership means looking beyond the down payment.
Can ITIN Buyers Use Every Mortgage or Down-Payment Assistance Program?
Not necessarily.
This is an important distinction.
Just because a mortgage program or down-payment assistance program exists doesn't mean every buyer will qualify for it.
Different conventional, government-backed, specialized and state assistance programs have their own borrower eligibility requirements.
For example, North Carolina has homebuyer assistance programs with specific eligibility requirements regarding factors such as income, credit, residency and the mortgage being used.
An ITIN borrower should therefore never assume that an advertised loan or assistance program automatically applies to their situation.
A qualified mortgage professional can determine which programs, if any, are available based on the buyer's individual circumstances.
What If I'm Not Ready to Buy Yet?
This might be the most important part of this entire conversation:
Not being ready today does not necessarily mean you can't become ready.
Imagine meeting with a lender and discovering that you need to improve your credit, reduce a particular debt, save additional money or establish a longer history of documented income.
At first, hearing “not yet” can feel disappointing.
But now imagine the alternative.
You spend another two years assuming you can't buy a home without ever finding out what was actually standing between you and qualification.
Knowing what needs to change gives you something extremely valuable:
A plan.
Maybe your plan is six months.
Maybe it's a year.
Maybe it's longer.
The important part is that instead of wondering whether homeownership is possible, you now know what you're working toward.
At DZ Pro Realty, we don't believe every first conversation has to end with:
“You're ready to buy a house!”
Sometimes an equally valuable conversation ends with:
“You're not there yet, but here's what your next step should be.”
Don't Start With the House. Start With the Plan.
We understand how easy it is to start browsing homes online.
You find a beautiful house.
You swipe through the pictures.
Suddenly you're imagining your couch in the living room.
You've already decided which bedroom belongs to which child.
You're picturing everyone around the kitchen island.
Maybe you've even mentally planned the backyard barbecue.
And then comes the question:
“Wait…can I actually afford this house?”
We recommend doing things in the opposite order.
First, understand your financial situation.
Then, explore your financing options.
Next, establish a comfortable budget.
Then start looking at homes.
Taking these steps first can make the home search much more productive—and potentially save you from falling in love with a property that doesn't fit your financial plan.
What Should I Have Ready Before Talking to a Lender?
You don't need to have everything figured out before asking questions.
However, depending on your situation, a lender may eventually request documentation such as:
- ITIN documentation
- Recent tax returns
- Pay stubs or other income documentation
- Bank statements
- Employment information
- Information about current debts
- Documentation of savings and other assets
- Identification
- Additional documentation required by the particular lender or loan program
This is not an exact mortgage checklist, because requirements vary.
The important thing is to begin organizing your financial documents if homeownership is one of your goals.
Does DZ Pro Realty Work With ITIN Buyers?
Yes.
DZ Pro Realty works with buyers throughout the Greater Charlotte area and surrounding communities, including families who may be navigating the American homebuying process for the first time.
We also understand how intimidating the process can feel when English isn't your preferred language or when your financial situation doesn't fit the traditional scenario you constantly hear about online.
That's why education and transparency are at the center of how we work.
Our job as your real estate professionals isn't to approve your mortgage. That decision belongs to the lender.
Our role is to help you understand the real estate process, connect you with appropriate professionals, search for homes that fit your goals, understand the contracts and deadlines involved in a transaction, negotiate on your behalf, and guide you from the beginning of the process through closing.
And we can guide you through that process in English or Spanish.
Stop Asking “Can I?” and Start Asking “What Would It Take?”
If you've been renting for years and have wondered whether buying a home could be possible, don't let uncertainty make the decision for you.
You don't need to know mortgage terminology.
You don't need to know which loan program you need.
You don't need to have perfect credit.
And you don't need to walk into the first conversation knowing whether you're ready to buy.
That's what the conversation is for.
Maybe you're ready now.
Maybe you're six months away.
Maybe you need a longer-term plan.
Finding out where you stand is the first step.
Let's Talk About Your Homeownership Goals
If buying a home has crossed your mind—even if you're unsure whether you qualify—DZ Pro Realty offers a free 30-minute real estate consultation where you can ask questions and talk about your goals.
We'll discuss where you are today, what you're hoping to accomplish and what your next step could look like.
If financing needs to be explored, we can help connect you with a lending professional who can evaluate your individual circumstances and explain potential options.
No pressure. No obligation. Just information, education and a clearer path forward.
Schedule your free 30-minute consultation with DZ Pro Realty today.
DZ Pro Realty is a real estate brokerage and is not a mortgage lender, tax advisor, attorney or immigration advisor. Mortgage availability, eligibility, interest rates, down-payment requirements and documentation requirements vary by lender, borrower and loan program and are subject to change. Nothing in this article constitutes a guarantee of financing or loan approval. Prospective buyers should consult qualified mortgage, tax and legal professionals regarding their individual circumstances.
Daniel Zambrano
Broker in Charge | DZ Pro Realty
or another way